
A Mini Story
Credit cards are Dementors in disguise.
They lurk over you, waiting until your lowest financial moment arrives, then they strike, with the force of a million Harry Potter spells.
“Financius eradicatus!!”
(Please don’t sue me J.K. Rowling!)
All of a sudden, poof! Your money is gone.
The end.
Where Did It All Go Wrong?
Well, it’s not that drastic, but these little plastic buggers are dangerous!
Credit cards are brilliant tools, don’t get me wrong, but if you don’t manage them correctly, they can cause an unholy amount of hassle, stress, anxiety… you get the picture.
This post stems from a personal experience I encountered about 7 years ago.
I remember getting accepted for my credit card just before I went travelling to Australia, which would have been in 2015. The details are a little hazy, but I remember enough to link all the pieces together.
Initially, I had the card for emergencies, in case I needed it abroad.
It turns out that I didn’t, because I managed to find a job down under which paid pretty well.
It was upon my return when the problems started to happen.
I lived a normal life after I came back as I am doing today – I worked, socialised, went on holidays, dated, saw family and friends… the whole shebang.
What I failed to realise though was they these little purchases on my credit card started to mount up. The hotel in Miami (4am drunk spending $200), the laptop from Currys for £700 or so, daily coffees, other things here and there. Okay, when I say little purchases, there were a few biggies in there.
Anyway, I just didn’t realise how much I was spending. I never wanted to use my own money because I didn’t want to run out, and it does sound very naive when I look back, but I honestly didn’t even bat an eyelid when it came to managing finances. It caused me so much anxiety when I reached the limit and the interest payments were close to £150 a months. Yes, the interest. That wasn’t a typo.
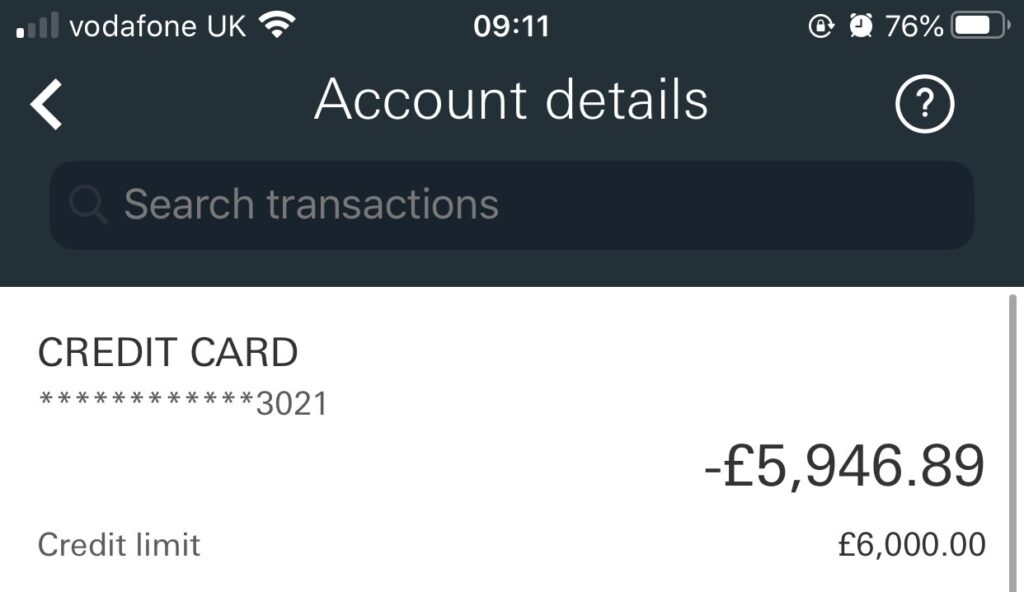
At one point dating back to 2020, just as the pandemic started, I was working for an insurance company and earning fairly poor money. Due to living alone and paying all the bills, it meant I couldn’t save enough money to pay off more of my credit card each month, to gradually reduce the balance. The interest per month was too high for me and I was stuck in their debt, forever.
What seemed like a reasonable balance to owe a company, £6,000, was in fact a considerable amount more because the balance was never reducing! The £150/month payment was just to keep my head above water. It was a financial nightmare and it caused some real problems for my mental health – I felt so trapped.
This is the where so many people struggle – they fail to ask for help. They become so consumed in their own debt they feel there’s no way out, just like I did. Sadly, at this point, some people’s light the end of their tunnels simply diminishes.
I was strong enough and able to ask for the help I so badly needed – I accepted a loan from a family member (0% interest) which not only cleared the whole credit card, but also a few other bits I had. I was so ashamed I had got myself into debt, but as equally determined to pay it back as soon as possible. I think it took 12 months, it was incredibly quick because my earnings had shot up almost 3 fold.
It was finally time to breathe.
What a relief that was.
It’s A Vicious Circle
Unless you actively make changes, this will go round and round in circles until you pluck up the courage to do something about it. It might come across as harsh, but it’s the reality. We get ourselves into these situations, so we are the only ones who can get us out of them.
I was lucky enough to have someone in the family to help me, but whoever you have to lean on, it’s better than suffering and struggling alone.
Your mental health is not worth compromising over money! You can always sort out money and earn more, once your mental health is gone, there’s sadly no coming back.
The Mental Strain
When you’re in debt, whether that’s £500 or £50,000, it plays on your mind – Naturally you might think £50k is worse – but it depends on how much you earn in your salary. If you’re earning £200k per annum, it might not seem so bad, whereas if you’re earning £25k, the alarm bells might ring a little louder and a little more frequently.
It’s all relative to the individual.
When we worry about things in life, in this scenario, more often than not, it has a knock-on effect; we worry at night, because our minds aren’t busy, so we start to dwell on things, we then fail to sleep a good amount of hours, so we start the next day out of sync just because we are worrying about 1 thing.
This can then have a knock-on effect and ‘de-synchronise’ your whole week. If you’re not careful, it can seep into the weekend.
With the correct help, debt can be solved, because it’s only money, it’s not the ‘be all and end all. Yes, finances play a very important role in our lives, but look, if we lost everything tomorrow, we’d start again, from scratch.
There are a lot of people who succumb to the pressures of debt; I recently heard on the news a father of two young children took his own life because he had a mountain of debt and less than £10 ‘to his name’.
The constant letters, calls, bailiffs and stress just got too much for him.
Heartbreaking.
Utterly heartbreaking.
Let’s Make It Compulsory
After my own personal dilemma, I feel that credit cards should be a mandatory part of a young persons’ education. Finances play a huge role in our lives, and if managed wrongly, the consequences and ramifications can be devastating.